
Narmi on Putting Agentic AI Inside Account-Opening Decisions
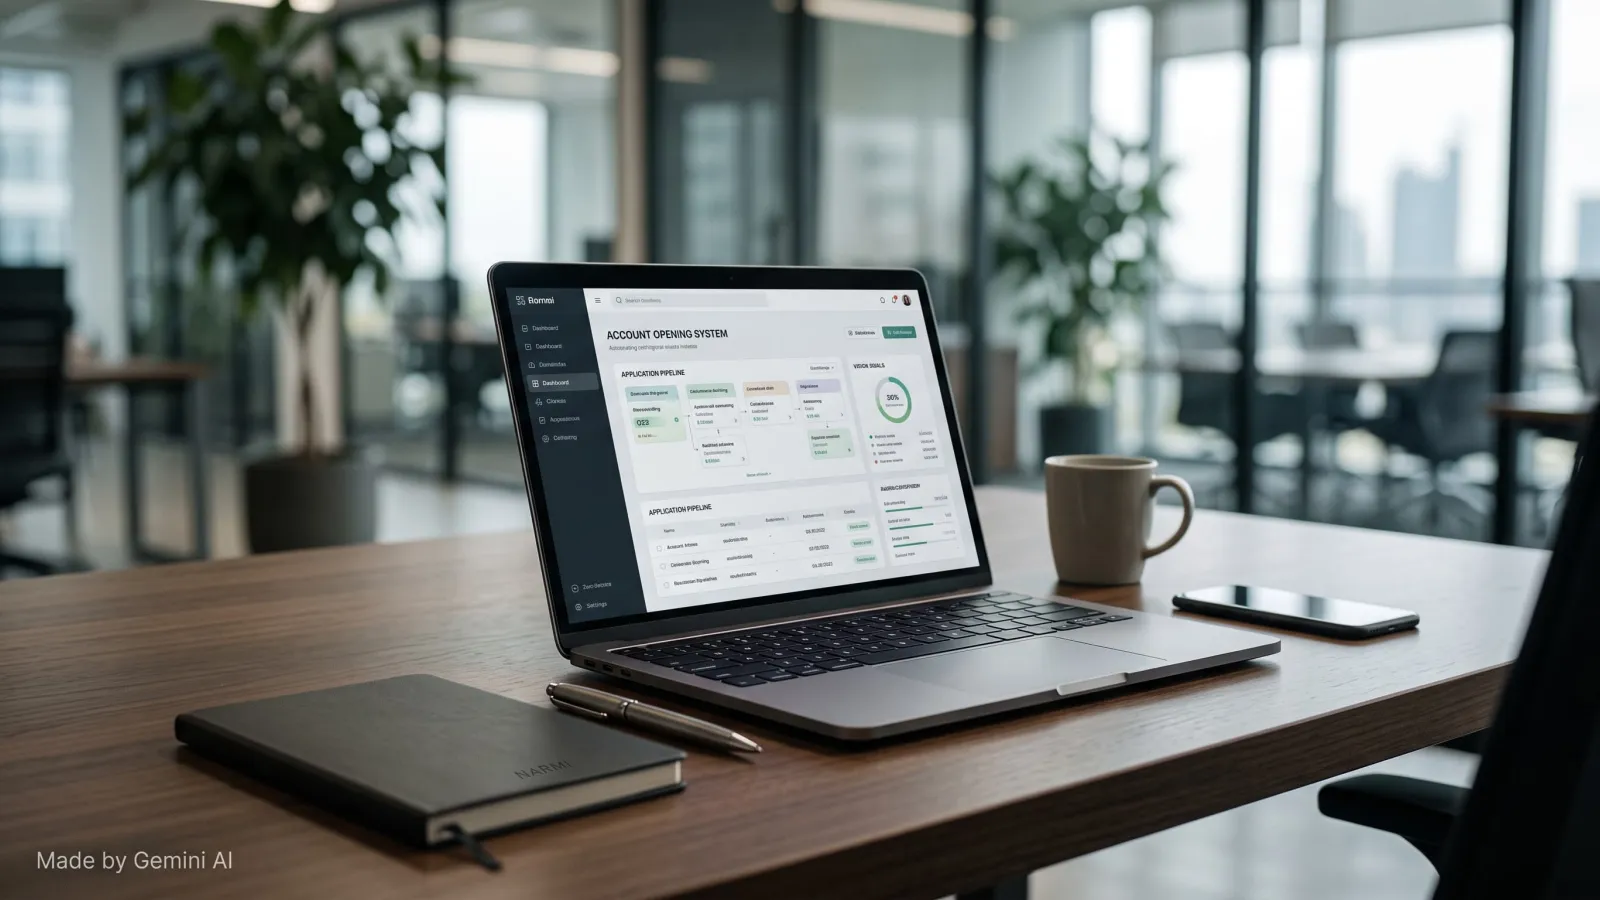
US banking technology provider Narmi has launched AI Decision Assist, an agentic AI tool that automates the manual review sitting behind account opening at community banks and credit unions.
The launch leans on a figure from Cornerstone Advisors' 2026 digital banking research: financial institutions are missing nearly 9,000 potential checking accounts a year to abandonment, barely moved from 9,572 in 2024.
Co-founder,
Narmi
Chris Griffin, co-founder of Narmi, and Nathan Gonzalez, the company's SVP of engineering, were both closely involved in building the tool. They answered The Fintech Times' written questions, and each answer is attributed as supplied.
Institutions are missing nearly 9,000 potential checking accounts a year to abandonment, against 9,572 in 2024. Why has that number barely moved, and what has the industry been fixing that was not the actual problem?
SVP of Engineering,
Narmi
Nathan Gonzalez: The abandonment rate obscures what's actually happening. Most institutions have solved digital application forms. Applicants sit in manual review queues for 24-48 hours while staff compile data from multiple systems, cross-reference compliance reports, and reconcile risk assessments. That's where the friction lives.
AI Decision Assist automates the work reviewers do manually. It doesn't speed up form-filling. It frees people from collating data and researching obscure fraud so they can actually review edge cases instead of grinding through data, with the potential for decision times to drop from days to hours. Whether that moves the overall abandonment number depends on adoption rates and execution, but for institutions deploying it correctly, we're seeing applicants move through the process fast enough that impatience stops being the reason they bail.
The industry has been fixing deposit-side friction but the back-office review remains a bottleneck. AI Decision Assist is a clear example of what we call Practical AI: it solves a real workflow problem and lets a lean team move at the speed of a much larger one.
AI DecisionAssist automates review of identity, risk and compliance information. That is a consequential place to put agentic AI. What happens when it gets one wrong, and who carries that, the institution or Narmi?
Chris Griffin: A financial institution will always be responsible for their risk and compliance programs in the United States. Automation is not a new concept for KYC/KYB and has been a time-tested value proposition in Narmi's product. However, financial institutions can still spend a lot of time researching the applications and applicants that fall into gray areas today. AI Decision Assist gives these expert decision makers superpowers to make more confident researched decisions.
The question regulators actually ask: can you defend your decisions? The system logs every data point, flag, recommendation, and what the human did and why, which provides an audit trail. Narmi's job is to make that auditable. It helps make sure your decisions are defensible. Everything's logged, everything's traceable. If a regulator asks why you approved or denied something, you have a real answer.
When a reviewer is under volume pressure and the system has produced a confident recommendation, how often does oversight become a rubber stamp? What have you built to stop that?
Chris Griffin: We work with our clients to ensure that scenarios that should be rubber-stamped turn into deterministic logic in their pre-existing automations in the Narmi platform. We actually monitor to help identify correlations between the ultimate human decisions and the factors that led to it. This helps reduce the volume of manual reviews so reviewers have more time to focus on those exceptional scenarios. We're building agentic workflows that require human judgment at the critical moment. That's what community FIs actually want, it's what regulators need: practical AI.
The UI requires active selection; there is no auto-approve. Each recommendation card uses a split button, and clicking 'Approve' or 'Deny' opens a confirmation modal showing the AI's reasoning and confidence score before the decision executes. When a reviewer overrides the recommendation, the system flags the override, requires notes explaining the decision, and logs it to the audit trail, feeding the reasoning back into the model for continuous improvement.
We also configure institution-specific risk thresholds. When the AI is calibrated to your actual history and tolerance, recommendations are more aligned to their policies and practices.
That said: if a bank is understaffed and a reviewer handles 500 complex manual reviews a week they will be making suboptimal decisions. It is very important that management and operators work together to find the right balance of time, tools, data, automations and expertise to be successful.
Cutting review from hours to minutes is a speed claim. Is there any evidence yet that it improves the quality of decisions, or only the pace of them?
Chris Griffin: Speed alone is worthless if it means faster decisions on thin data. What we're actually measuring is operational leverage: a small team operating at the scale of a much larger one.
A reviewer that used to spend hours jumping between systems, re-reading reports, manually cross-checking data, conducting open ended research, and manually following up with the applicant was simply operating inefficiently. Now they start with a fully researched case and clear recommended next-steps. The follow-up outreach to applicants is also further automated.
On quality, we're tracking approval rates, operator overrides and approval-to-charge-off ratios. Early data suggests the tool tightens consistency with fewer outliers and fewer decisions that look arbitrary side-by-side. Some individual reviewers were running too loose; some too tight. The AI tends to normalize them toward their own historical norms.
While we don't yet have the years of fraud data needed to claim that AI-assisted decisions outperform expert judgment, we have made the process more auditable, more consistent, and faster without sacrificing rigor.
Community banks and credit unions are the institutions least able to absorb a compliance failure. What should a smaller institution have in place before it lets an AI system anywhere near an account-opening decision?
Nathan Gonzalez: You can't deploy AI practically without practical governance. Three non-negotiables are:
- Audit capability. Pull random samples of decisions and trace them. What data went in? What did the AI recommend? What did the reviewer do? Can you explain the full chain to an auditor in five minutes? If you can't, you're not ready.
- Threshold calibration. As we work together towards eventual automation, you decide what this tool handles versus what stays escalated. For a credit union, that might mean AI handles routine existing members and obvious fraud, while anything over $50K or complex ownership structures go to a human. That decision belongs to your institution and always will.
- Reviewer training and spot-checks. Staff need to understand what '87 per cent confidence' actually means. Quarterly, pull 20 decisions and have a senior person review them independently. Look for patterns your reviewers might be missing.
Institutions fail when they treat this like set-it-and-forget-it. Ones that succeed treat it like any control: you own it, you monitor it, you adjust it. Narmi makes monitoring possible. You do the work.
Fraudsters also prefer a six-minute account. How do you square accelerating approval with rising account-opening fraud, and what does the tool do differently for a suspicious application?
Chris Griffin: Speed helps fraudsters if controls are weak, so the question becomes whether your controls are actually strong.
A slow system with weak controls loses to fraud, wastes internal resources and simply delays the fraud event by a few days. A fast system with strong controls catches fraud at scale. The difference comes down to consistency. Human reviewers catching fraud depends on attention, pattern familiarity, and the noise level that day. AI doesn't get tired and doesn't miss a pattern because it's already reviewed 30 applications.
On higher-risk applications, the agent flags the specific signals it found and recommends escalation rather than guessing, so a reviewer can route genuine anomalies to a supervisor quickly if appropriate. Because the analysis is ready the moment the application opens (roughly 15 to 30 seconds after it enters Manual Review), reviewers spend their time confirming and acting on the findings rather than assembling them. The human always makes the final call.
The model takes into account each institution's historical decisioning data. It learns your risk tolerance, your decisioning behaviors, and your internal policies.
Community banking has spent years being told technology will close the gap with the large institutions. Why is this different, and what would you accept as evidence in two years that it was not?
Nathan Gonzalez: Here's what I'd measure:
- Customer side: A bank using this tool should cut decision time measurably while keeping default rates flat. Not 'faster and hoping it doesn't hurt'; faster with accountability. Decision time from 48 hours to 4 hours, defaults unchanged: that's evidence.
- Market side: Can a $500M credit union match the decisioning speed and audit capability of a $50B bank on account opening? Yes. With the right technology partner, they can move just as fast and audit just as thoroughly. They won't replicate the mega bank's entire tech infrastructure, but they don't need to. They're competing on what matters to their members.
- Behavior change: Community FIs aren't behind, they're constrained. They have risk judgment, relationships, culture. They may lack operational leverage to move quickly. In two years, are they growing faster? Acquiring members from online-only banks? Competing aggressively in checking instead of ceding it? If the tool works, you see ambition shift, not just speed shift.
That said, we're already seeing traction. Over 60 per cent of our community FI partners have signed our AI terms and conditions. Three quarters of our AI products are at 50 per cent adoption across the institutions that are eligible. That's meaningful because these folks aren't early adopters; community FIs have been moving deliberately, especially on AI. They're adopting Narmi's practical AI because it actually solves their problem.