
Analysis

Fintech

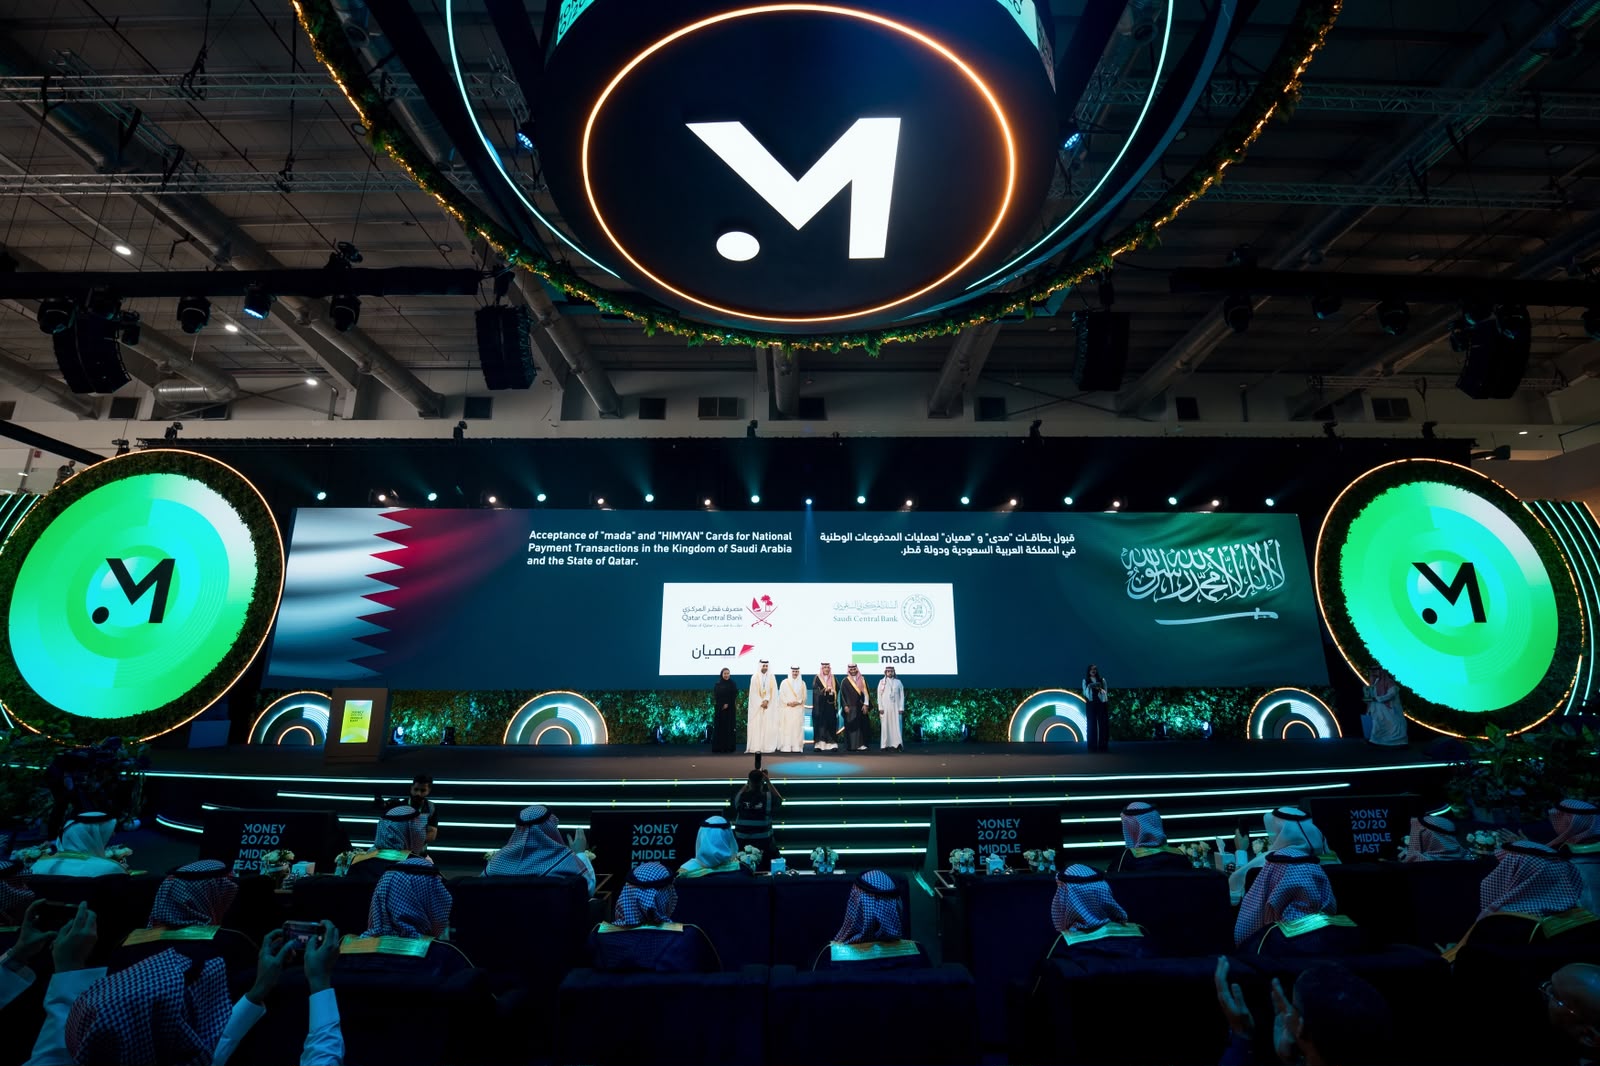
Riyadh day two: a live card link, $329.5m for barq, SME capital

Central bank governors' live card payment, barq's $329.5m Series A and a new SME financing fund made Money20/20 Middle East's second day about capital.
Fintech

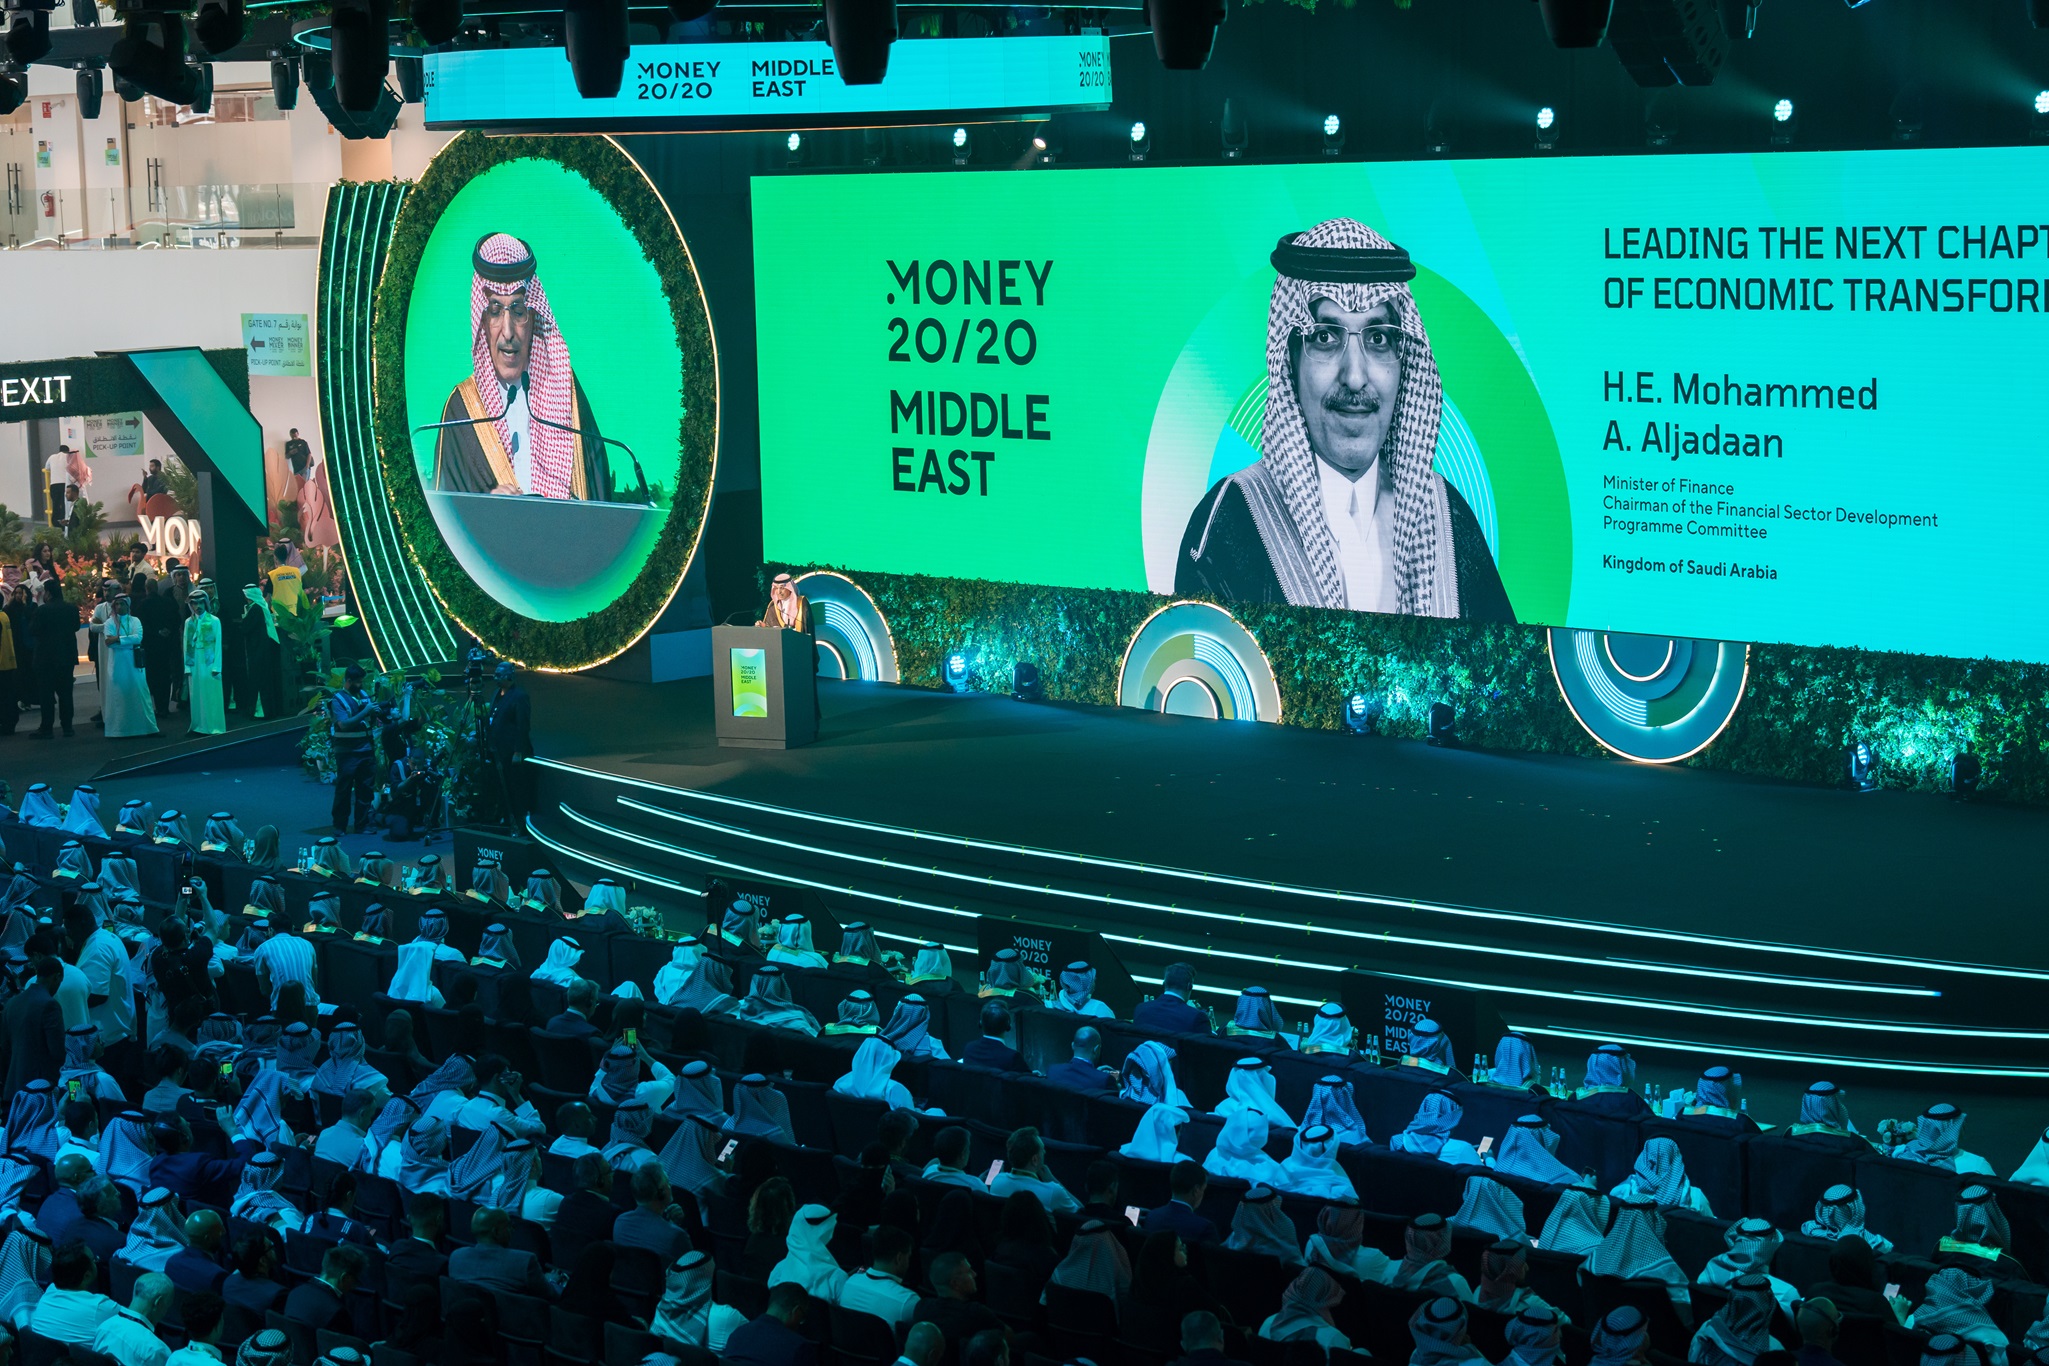
Riyadh day one: Tabby's $6.5bn and the licences behind it

Tabby's $6.5bn valuation, a SAR 500m SME financing fund and payouts into six new markets opened Money20/20 Middle East, each built on a licence.
Blockchain
Cryptography
Fintech

Stablecoin 101: how stablecoins work and why they matter

What a stablecoin is, what backs the dollar, why $300bn now sits in them, and how the US, EU and UK rules written in the last two years change the picture.
Blockchain
Cryptography
Fintech

How stablecoin settlement works in cross-border payments

Follow a payment from Manchester to Lagos to see where the stablecoin removes the correspondent banks, what it costs, and why the last mile is still hard.
Blockchain
Cryptography
Fintech

Tokenised deposits explained: what banks are building next

A tokenised deposit is a bank's own money on a shared ledger. Here is how it differs from a stablecoin, who has one live, and why the two will coexist.
Cryptography
Retail & E-Commerce
Fintech

How payment processing fees work in fintech

Take one card payment apart: interchange to the issuer, scheme fees to Visa or Mastercard, margin to the acquirer, and why the new rails are aimed at all three.
Subscribe to Analysis