Checkout.com moves into stores as omnichannel payments race heats up
Checkout.com, the London-headquartered payments processor that the company says will handle $480 billion in global e-commerce volume in 2026, is extending its platform into physical retail for the first time. The move pits a digital-native acquirer against established point-of-sale incumbents such as Adyen, Stripe and Worldline, all of whom have long competed for the unified commerce wallet.
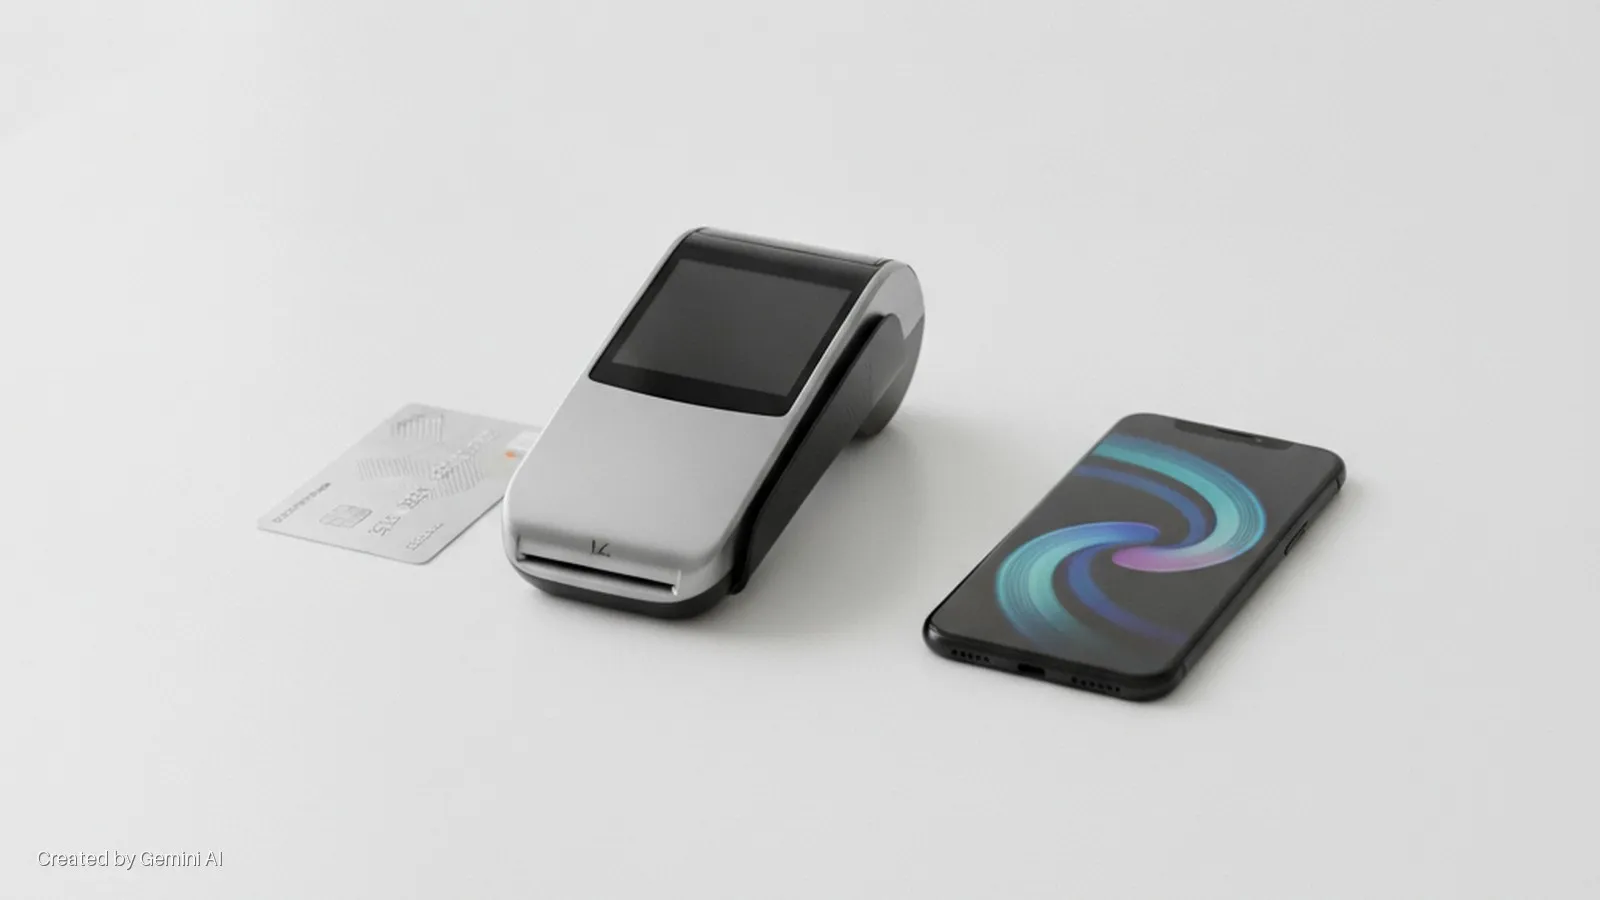
The expansion is built on a software-led, device-agnostic architecture: rather than bundling proprietary hardware, Checkout.com connects to terminals merchants already own or choose themselves. A single Unified Payments API spans both online and in-person transactions, with shared settlement infrastructure and a common dashboard. That architecture is a deliberate bet that the industry's next margin battle is won at the software layer, not the hardware layer.
Mollie anchors the European launch
European payments platform Mollie, which serves more than 350,000 businesses following its combination with GoCardless, is the anchor partner for the initial UK and EEA rollout. The structure preserves Mollie's control over customer experience and hardware selection while placing Checkout.com's acquiring engine beneath it. Rogier Schoute, Mollie's Chief Product Officer, described in-person payments as "one of the fastest-growing areas of our business, driven by hundreds of thousands of European merchants looking to unify their physical and digital sales."
For Checkout.com, the timing is deliberate. Chief Revenue Officer Antoine Nougué pointed to the company's "sustained profitability and growing margins" as the financial foundation for the investment, framing it as merchant-demand-led rather than speculative. The company reports more than 500 code releases per day and sub-500ms transaction latency across its multi-region infrastructure, figures designed to reassure enterprise merchants accustomed to the reliability benchmarks set by card scheme networks directly.
The omnichannel convergence bet
The strategic read-across here extends well beyond payments infrastructure. The drive to unify online and in-store transaction rails is one expression of a broader convergence between digital commerce platforms and physical retail operations. As large enterprise merchants push toward truly unified commerce, the acquirer who owns both channels holds a structural advantage in data, fraud modelling, and settlement economics. That is the competitive logic that Adyen used to displace incumbent point-of-sale providers across European retail over the prior decade.
From a capital-allocation perspective, the payments infrastructure layer has attracted sustained institutional interest precisely because it sits at the intersection of fintech, retail technology, and data infrastructure. Checkout.com's profitable balance sheet means this expansion is self-funded rather than venture-backed, a positioning that resonates differently in a rate environment where growth-at-any-cost fintech stories have lost credibility with investors. The company's client roster, spanning Microsoft, Uber, Klarna, Spotify and eBay, also signals that the in-person push is aimed squarely at enterprise complexity, not SME simplicity.
The US market, where Checkout.com says it will expand after the UK and EEA launch, adds a further dimension. American in-person payments remain heavily contested, with domestic processors, card networks and neobank-adjacent players all competing on software differentiation. A device-agnostic acquirer with a profitable European base and $480 billion in annual processing volume enters that market with credibility, but faces entrenched relationships and a regulatory environment that has historically favoured incumbents. Whether the Mollie partnership model translates to US distribution, where Mollie's footprint is smaller, will be the operational question to watch as the rollout progresses into 2027.