
Mercury Systems expands Phoenix plant to meet defence electronics surge
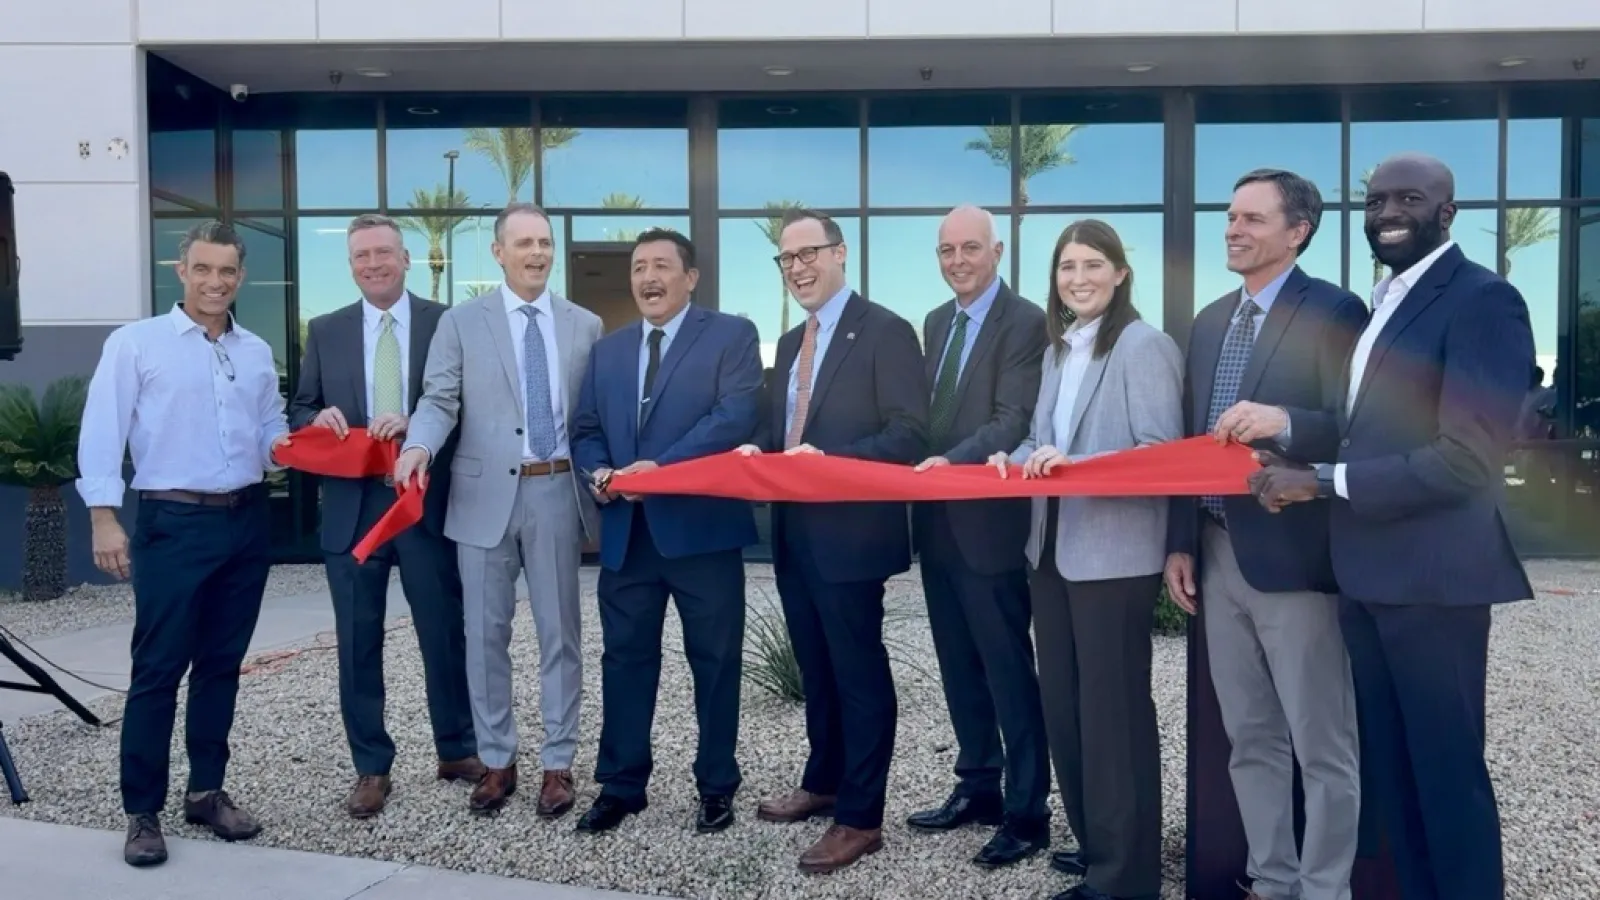
Mercury Systems (Nasdaq: MRCY) has opened a 50,000 sq ft automated manufacturing facility on its existing Phoenix campus, adding production headroom for high-performance electronics that sit at the heart of modern military platforms. The expansion, which began operations in the third quarter of Mercury's fiscal year 2026, is intended to shorten delivery timelines through vertical integration and to absorb what the company describes as record bookings and backlog heading into the new fiscal year.
The Phoenix site is already Mercury's largest manufacturing centre, employing more than 400 people. It produces printed circuit board assemblies, high-performance space drives, advanced packaging technologies, and the memory solutions that must survive extreme operating environments, from armoured vehicles to orbital systems. The new building is designed to scale output on the company's Common Processing Architecture programmes, a product family that provides the signal and data processing backbone for edge-deployed military systems.
Vertical integration as a strategic lever
Tod Brindlinger, Mercury's Senior Vice President of Operations, pointed directly to demand-side pressure as the rationale: "We see strong demand signals across our portfolio, ending fiscal year 2026 with record bookings and backlog that our expanded production facility will help us to execute against." The company says the expansion is expected to create more than 50 jobs over the next twelve months.
The investment is a textbook response to the structural shift underway in Western defence procurement. After years of outsourcing component manufacturing to lower-cost geographies, a growing number of prime contractors and Tier 2 suppliers are bringing critical production back onshore, partly to satisfy ITAR and DFARS compliance requirements, and partly to reduce exposure to supply-chain volatility that proved costly during the post-pandemic component shortages. Mercury's move to expand domestic, vertically integrated capacity puts it in line with a broader reshoring logic that has also driven investment decisions at peers across the US defence electronics supply chain.
Cross-sector read-across: defence spend meets the compute build-out
The convergence angle for Disrupts readers is the overlap between defence electronics demand and the wider race to deploy processing power at the edge. Mercury's Common Processing Architecture is not a niche programme; it supplies signal processing to platforms across air, land, sea and space domains, making it a de facto infrastructure layer for multi-domain operations. The same architectural trend, pushing high-performance compute closer to the point of action, is driving investment in commercial edge AI deployments, autonomous vehicle compute stacks, and low-earth-orbit satellite processing. Defence procurement is, in effect, acting as a funded proving ground for ruggedised edge compute that will eventually migrate into civilian applications.
For capital allocators tracking the defence-tech space, Mercury's record backlog is a useful leading indicator. Western governments have committed to sustained increases in defence spending, NATO members are under pressure to reach or exceed the 2% of GDP threshold, and several are moving towards 3%, and that political commitment is now translating into signed contracts. Tier 2 suppliers with the manufacturing infrastructure to execute on delivery timelines, rather than simply win bids, are likely to attract growing interest from institutional investors who have historically underweighted the supply chain relative to the prime contractors. The Phoenix expansion signals Mercury is positioning itself precisely in that gap.
Looking further out, the automation investment embedded in the new facility carries its own second-order implications. Highly automated defence manufacturing plants reduce unit labour cost and improve yield consistency, but they also increase fixed-cost exposure during any drawdown in programme funding. Investors will be watching whether Mercury's backlog concentration, and the geopolitical conditions sustaining it, hold through the next US federal budget cycle.