
World ID targets banking fraud as AI impersonation risk soars
Tools for Humanity, the contributor organisation behind the World project, has unveiled World ID for banking and finance at Money20/20 in Las Vegas, extending its biometric proof-of-human infrastructure into one of the highest-stakes arenas for AI-driven fraud. The launch marks the first industry-vertical focus for World ID, targeting the specific threat of deepfake impersonation, synthetic identities, and AI-generated agents operating inside financial institutions.
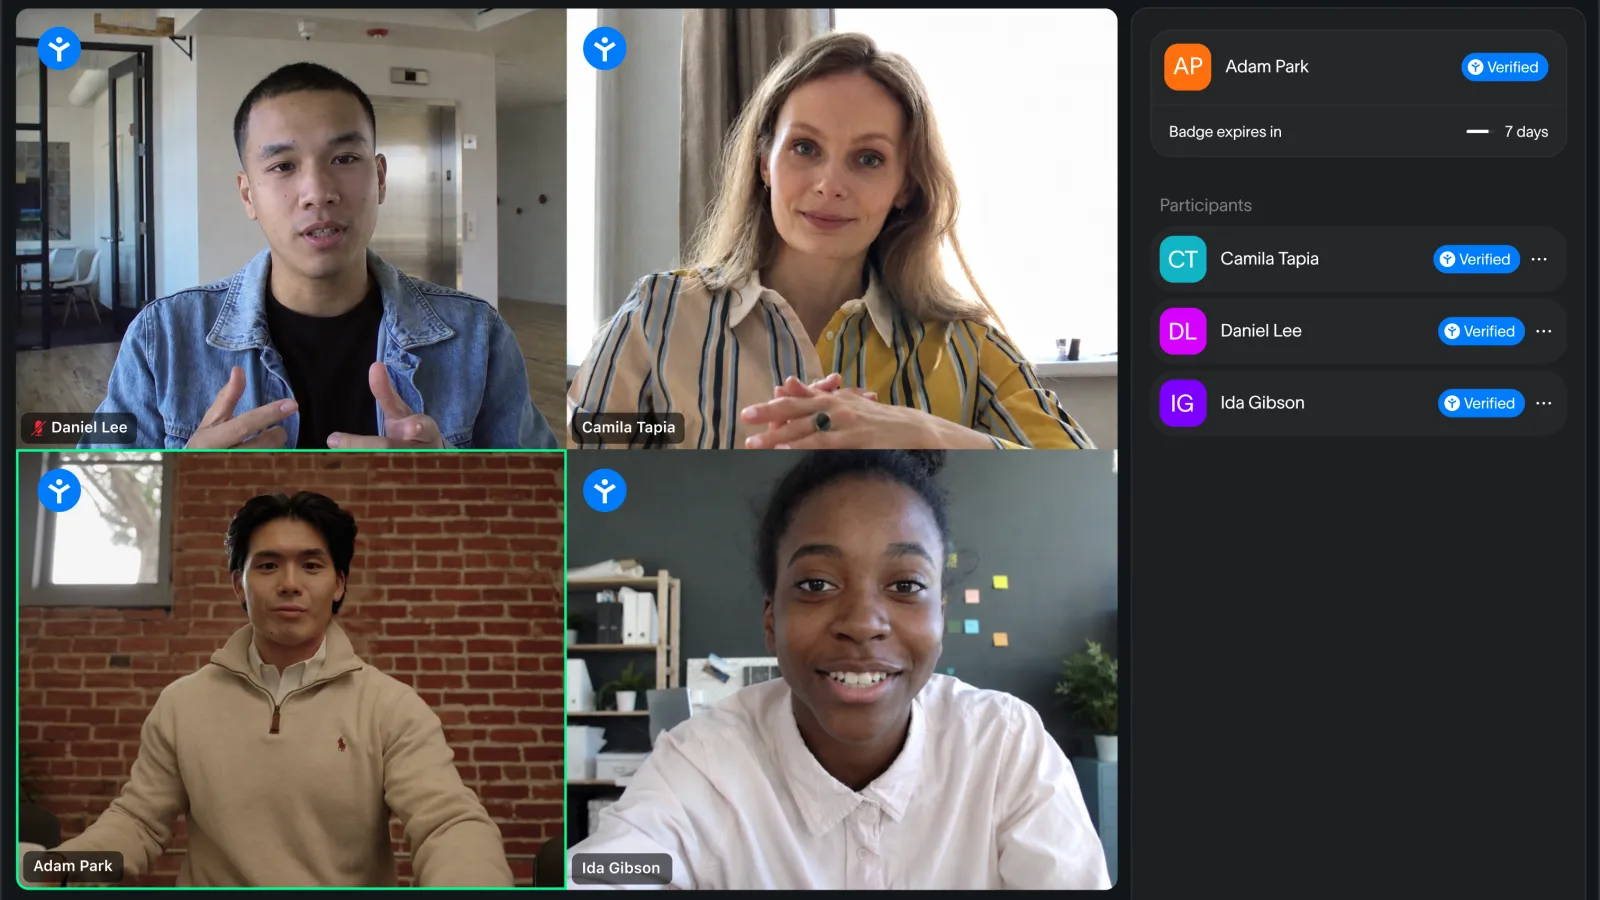
The offering bundles three components: the World ID app, an identity wallet for managing and presenting cryptographically verified human credentials; World ID for Zoom, which confirms a counterparty is human during video communications; and World ID for Agents, which allows a verified individual to delegate their credentials to an AI agent acting on their behalf. The suite is now generally available, with World ID for Zoom also entering Zoom's independent software vendor exchange programme.
The fraud calculus
The commercial logic is hard to dispute. Deloitte projects that AI-enabled fraud losses in the United States alone could reach $40 billion by 2027, compared with an estimated $12.3 billion in 2023. That near-tripling in four years reflects both the rapid commoditisation of generative AI tools capable of producing convincing synthetic voices and video, and the migration of high-value financial interactions into digital channels where visual verification has traditionally offered some assurance.
World is working with a group of design partners that spans the capital-markets spectrum: Bain Capital, VanEck Funds, and Pantera Capital are named alongside OpenExchange and creative firm Outtake. The breadth of that cohort, ranging from traditional asset management to crypto-native funds, suggests that the verification problem is sector-agnostic within finance. What unites them is digital interaction volume and the asymmetric cost of a single fraudulent transaction slipping through.
Sandro Herbig, president at Tools for Humanity, framed the shift as a structural change in enterprise trust requirements: "As AI becomes increasingly prevalent in all aspects of our lives, enterprises are requesting individuals provide 'Proofs' about themselves to help mitigate fraud and increase trust."
Convergence read-across: identity infrastructure as financial rails
The deeper strategic question World ID poses is whether proof-of-human infrastructure is becoming a foundational layer for the digital economy in the same way that SSL certificates became a non-negotiable layer for web commerce in the late 1990s. If it is, then the company capturing the standard stands to occupy a position of considerable systemic leverage.
The cryptographic architecture is notable: World says its verification capabilities are quantum-secure, positioning the system for a post-quantum cryptography environment that regulators in the US, UK, and EU are beginning to mandate for financial institutions. That places World ID at an intersection of three converging pressures on banks: the AI fraud wave, the post-quantum migration timeline, and increasing regulatory scrutiny of digital identity verification under frameworks such as eIDAS 2.0 in Europe.
For investors tracking capital flows across the cybersecurity and fintech corridors, the World ID launch raises a broader question about market structure. Incumbent identity verification players, including incumbent KYC providers and biometric vendors, have largely concentrated on onboarding workflows. World ID's ambition is runtime verification, confirming humanity not just at sign-up but during every consequential digital interaction. That is a meaningfully different product surface, and one that existing players have not yet fully addressed.
The project reports more than 18 million holders of its Proof of Human credential globally, a user base that, if it scales into enterprise financial services workflows, could give World a network-effect moat that pure-software identity vendors would struggle to replicate. The next test will be whether regulated financial institutions, with their demanding compliance and data-residency requirements, will accept a credential rooted in a consumer biometric network as their primary trust mechanism.