LuLu Financial targets UAE's 1.33m SMEs via Purpleplum fintech tie-up
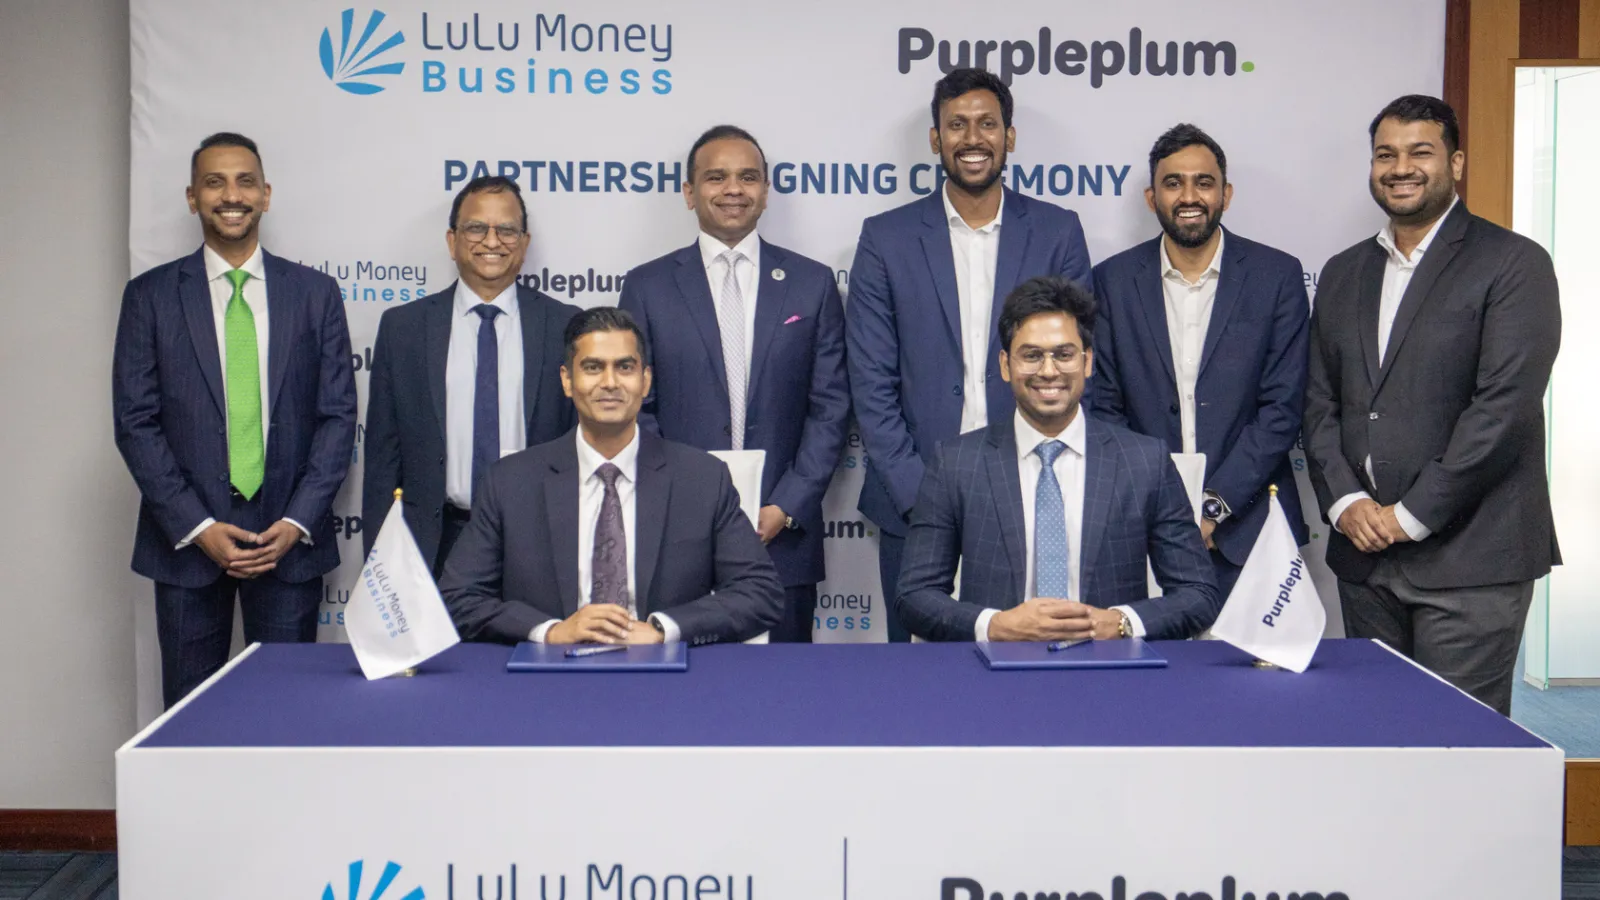
LuLu Financial Holdings (LFH) and fintech infrastructure provider Purpleplum have formalised a partnership to deliver an integrated digital financial services platform for businesses in the UAE, targeting a domestic SME sector that the UAE Ministry of Economy and Tourism says contributes 63% of national GDP and employs more than 85% of the private-sector workforce.
The combined proposition, branded LuLu Money Business, bundles digital business accounts, cross-border remittances, cards, payments and WPS payroll services into a single digital experience. Accounts are issued through ruya, an Islamic bank licensed by the Central Bank of the UAE, making the product compliant with sharia principles from day one, a structural requirement in a Gulf market where Islamic finance is the dominant paradigm rather than a niche offering.
Agentic AI as onboarding infrastructure
What distinguishes the deployment from a standard Banking-as-a-Service integration is the use of agentic AI workflows to manage business account-opening journeys. LFH says thousands of registered business applications are currently under review through the platform. For Purpleplum, whose infrastructure already supports 1.1 million active users and has processed 520 million transactions, this marks its most prominent regional anchor deal and positions Abu Dhabi and Dubai as the launchpad for a broader GCC and Asia-Pacific push over the next 12 to 24 months.
Adeeb Ahamed, Managing Director of LuLu Financial Holdings, framed the partnership as a modernisation of established financial rails rather than a ground-up build: "We are combining its modular, core-agnostic orchestration platform with our existing infrastructure to modernise how these services are delivered and unlock greater value from established financial rails."
The longer-term roadmap extends well beyond payments. LFH has signalled plans to layer working-capital lending, invoice and trade financing, corporate credit, receivables management, accounting automation and treasury services onto the platform, effectively building a vertically integrated SME financial operating system. That ambition sits closer to the embedded-finance model pioneered by fintechs such as Shopify Balance or Tide in the UK than to a conventional exchange house diversifying into digital.
Convergence read-across: GCC as a testbed for AI-native banking
The strategic significance of this deal extends beyond its immediate UAE footprint. The GCC is rapidly becoming one of the most permissive and capital-rich environments for AI-native financial infrastructure globally. Progressive central-bank licensing frameworks in the UAE and Saudi Arabia, combined with sovereign-wealth appetite for homegrown fintech champions, are creating conditions that Western markets, constrained by legacy prudential regimes and slower digital-ID infrastructure, struggle to replicate at comparable speed.
For infrastructure players like Purpleplum, the GCC represents a rare combination: large underserved SME populations, digitally engaged business owners, and regulatory sandboxes that allow rapid product iteration. That dynamic is attracting a cohort of core-agnostic platform providers, firms that sit between legacy core-banking systems and the end customer, orchestrating products across multiple rails without replacing the underlying infrastructure. Mambu, Thought Machine and Temenos have pursued similar positioning in European and Asian markets; Purpleplum is betting the Middle East iteration of that race is still open.
The cross-border dimension adds further strategic weight. LFH's existing footprint across the Indian subcontinent and Asia-Pacific means a proven LuLu Money Business model in the UAE could be replicated across corridors where Gulf remittance flows are already structurally significant. India alone receives the world's largest volume of inbound remittances, and LFH's established exchange network provides distribution infrastructure that pure-play fintechs typically spend years building. The question for investors watching this space is whether an embedded-finance layer bolted onto a remittance network can command fintech-grade multiples, or whether the legacy exchange-house identity anchors the valuation conversation to more modest financial-services comparables.