
Mastercard and Trip.com launch agentic commerce push in travel
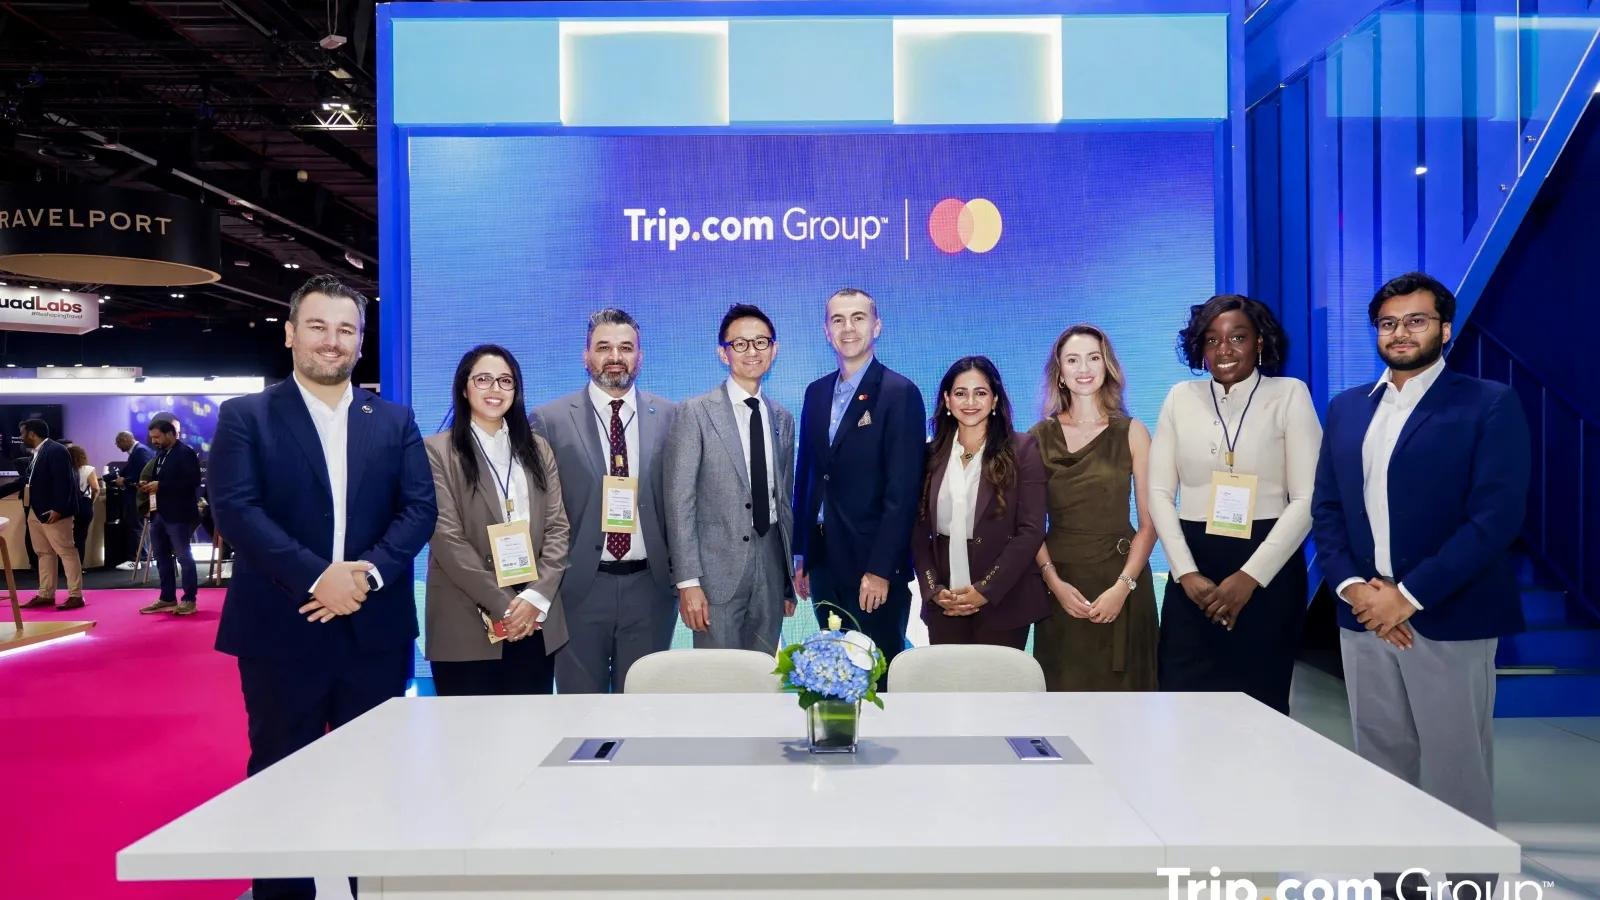
Mastercard, Trip.com Group and payments enabler Network International have unveiled a collaborative framework designed to let AI agents handle the full arc of a travel transaction, from destination discovery through to payment authorisation, without requiring the consumer to interact manually at each step. The initiative, showcased at the Arabian Travel Market in Dubai, positions the Gulf as the launch geography for what the partners describe as the next structural shift in digital commerce.
At the centre of the arrangement is Mastercard's Agent Suite for Merchants, a toolkit that allows businesses to embed autonomous shopping agents into existing e-commerce environments. Trip.com's AI agent TripGenie is the first named implementation, handling search, comparison and purchase within the Trip.com ecosystem. Network International, the region's dominant payments infrastructure provider, supplies the acquiring and processing layer that makes the transactions settleable across the Middle East and Africa.
Agentic commerce as a payments architecture question
What makes this more than a marketing showcase is the underlying payments-infrastructure logic. Agentic commerce, where a software agent acts on a consumer's standing authorisation rather than a point-of-sale approval, breaks the traditional transaction model. The consumer delegates, the agent executes, and the merchant never sees a human at the checkout. That creates novel fraud, liability and authentication questions that Mastercard is positioning its tokenisation and authentication stack to resolve. Schubert Lou, CEO of Trip.com, framed the ambition directly: "AI is changing travel from a search experience into a much more intelligent and personalised journey... AI agents, operating securely and with the traveller's authorisation, can intelligently facilitate travel-related transactions."
The commercial launch is expected in early 2027, initially covering attractions and ancillary travel services before expanding to core flight and hotel inventory. The phased approach suggests the partners are navigating both technical integration complexity and the regulatory appetite for delegated consumer payments, particularly in jurisdictions across the Middle East and Africa where Network International operates.
Cross-sector read-across: fintech infrastructure meets the agentic workforce
The convergence angle here runs in two directions. First, for the payments industry, agentic commerce represents a structural displacement of card-present and click-to-pay models. If the agent holds a tokenised credential and acts autonomously, the traditional checkout funnel collapses, and with it the screen real estate that card networks and buy-now-pay-later providers have competed over for a decade. Mastercard's early positioning in the merchant-agent layer is a defensive as much as an offensive move.
Second, for the broader agentic-AI investment thesis, travel is a high-frequency, high-complexity vertical that functions as a useful stress test. A single trip booking can involve seven or eight discrete commercial transactions across airlines, hotels, ground transport, insurance and experiences. If an AI agent can handle all of those within a single authorisation framework, the blueprint transfers readily to retail, healthcare appointments, and corporate procurement, sectors where agentic commerce is still largely theoretical. Investors tracking the agentic-workforce theme, particularly those already backing players in autonomous AI orchestration, should treat the travel vertical as the canary.
The Gulf geography is not incidental. The UAE and Saudi Arabia have both signalled through sovereign-wealth and regulatory moves that they intend to be early adopters of AI-native commerce infrastructure, and Network International's footprint across MEA gives the consortium a practical distribution network that extends well beyond the showcase event. Whether regulators elsewhere, particularly in the EU under the AI Act's evolving agent-liability provisions, move fast enough to allow equivalent commercial rollouts by 2027 remains the open question.