
Pebblio's Alex Postlethwaite on the UK's unofficial overdraft
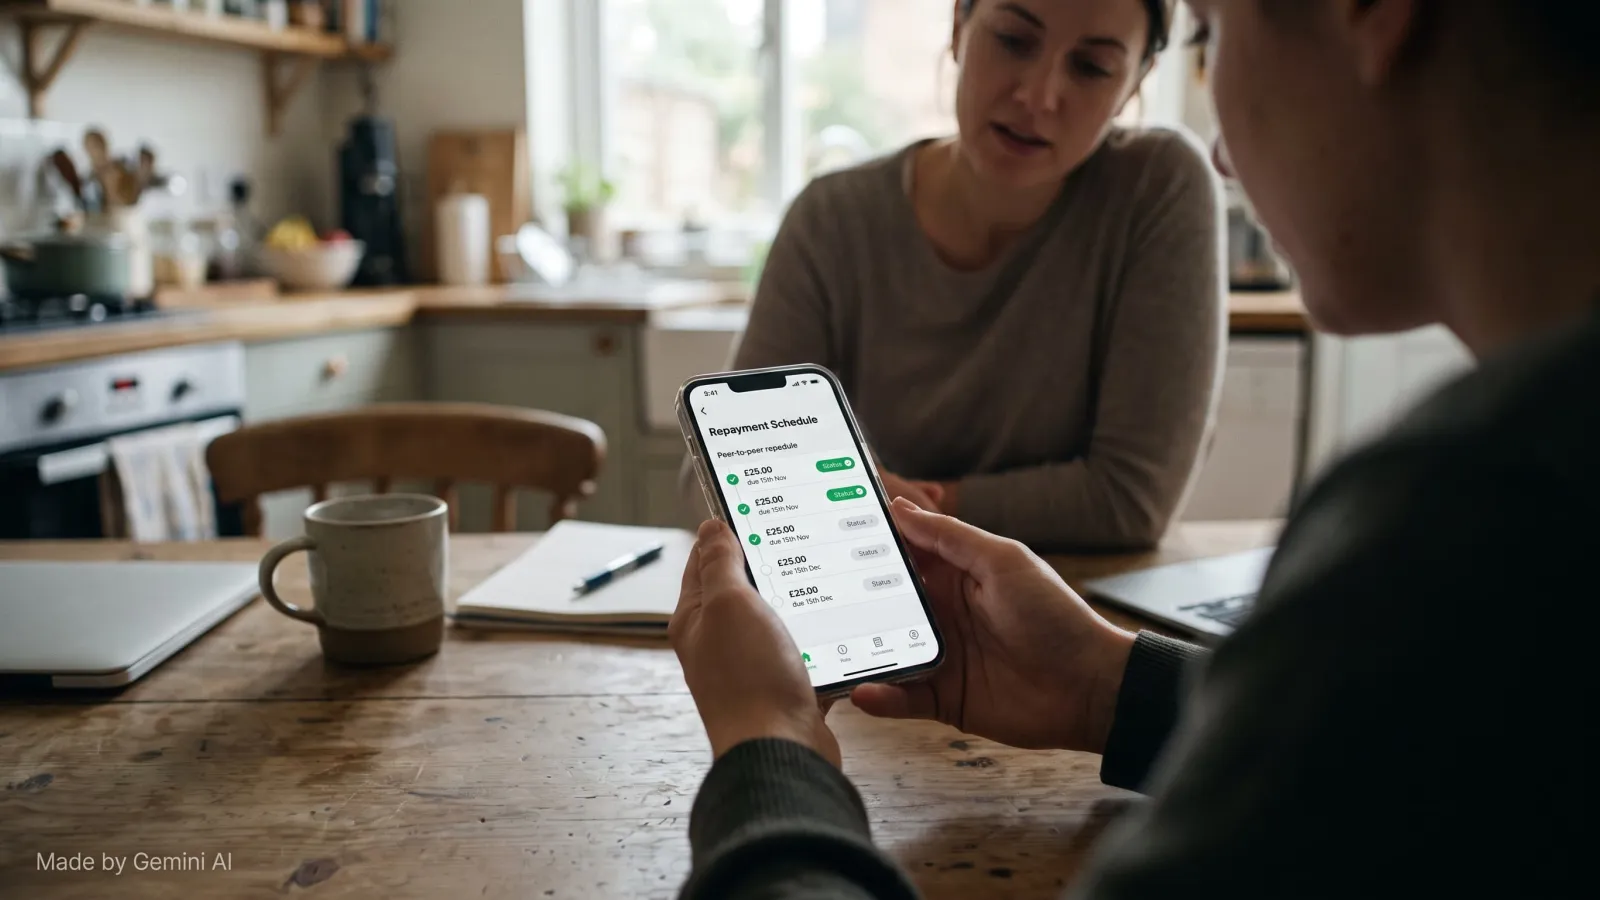
Half of UK adults lent or borrowed money within their family or friendship group in the past year, according to research commissioned by Pebblio, a UK web application that helps friends and family put interest-free loans between themselves in writing.
Pebblio is a record-keeping tool, not a lender: it never holds money, never provides capital and never collects on anyone's behalf.
Chartered Accountant
& founder, Pebblio
Its founder, Alex Postlethwaite, is a chartered accountant who spent more than ten years in private equity finance and operations before building the product. He spoke to Disrupts about what the research found, why informal lending has become an unofficial overdraft, where the arrangements go wrong, and what policymakers and lenders should take from the scale of it.
The lender carries the anxiety
The finding that surprised Postlethwaite most was how differently the two sides of a loan see it. “People who had only lent were almost twice as likely as people who had only borrowed to say a loan had led to a repayment problem or misunderstanding: 46 per cent against 24 per cent,” he said. “Every loan has two people in it, so that gap suggests many borrowers don't realise, or don't like to admit, that the person who helped them is worried. The lender carries the anxiety.”
Nor is it a behaviour confined to people locked out of credit. Households earning 100,000 pounds or more were the most active income group, with 69 per cent having lent or borrowed, and the share who had borrowed was about a third at both the top and bottom of the income range. “This isn't a fringe behaviour of people locked out of credit. It's how the country gets from one payday to the next.” More than half of those who lend or borrow do so at least every few months, and nearly half moved 250 pounds or more over the year, yet three in four keep no formal record.
The fastest, cheapest credit there is
Postlethwaite's explanation for why family and friends have become an unofficial overdraft is blunt. “Because for most people it's the fastest, cheapest and least judgemental credit there is. No application, no credit check, no interest, no fees. When the boiler breaks and payday is ten days off, a sibling or a friend is often the only option that says yes the same day.”
The data points at thin buffers: among people who had borrowed, nearly three in four said their last loan was for an unexpected expense or a gap before payday, and almost one in five who lend or borrow do it at least monthly. “That isn't a one-off favour. It's an overdraft facility, run on trust.” He set that against the wider picture: inflation back at 3.1 per cent in August, the energy price cap rising 4 per cent in October, frozen tax thresholds, and the FCA's most recent Financial Lives survey putting 13 million adults on low financial resilience with nearly a third holding under 1,000 pounds in cash savings. The same survey found 3.2 million people had been declined credit in the previous two years, and around one in five of them borrowed from family or friends instead. “When the formal system says no, families say yes.”
Where it goes wrong
Two in five people in the research reported a repayment misunderstanding, and Postlethwaite said the failure is rarely at the moment the money changes hands. “It goes wrong later, in the silence. Most of these loans are agreed in a single sentence, ‘pay me back when you can', and 59 per cent of people who lend or borrow have nothing written down, not even a text.” In 28 per cent of people's most recent loans there was no agreed repayment date at all. The risk climbs with the stakes, from 24 per cent of loans under 100 pounds to around half of those between 250 and 1,000 pounds, and with frequency, reaching 56 per cent among people lending or borrowing several times a month.
“Then comes the part nobody wants: asking for it back. A quarter of people who don't lend or borrow say reminding someone is too awkward. So lenders say nothing, resentment builds, and the borrower may not even realise.” The human cost, he said, is the relationship: nearly half of those who do not lend or borrow hold back out of worry about damaging it, not being repaid or having to chase, and separate Ipsos research for Fair4All Finance found 17 per cent of people who borrowed from friends said it weakened the friendship. “And once burned, people stop helping, which removes the safest source of credit many households have.”
Writing it down
The idea for Pebblio came from the contrast between his working life and his friends' kitchen tables. “In that world nothing moves without paperwork. Every commitment is written down, every cash flow reconciled, and nobody finds that insulting. It's what lets people trust each other with large sums. Then at home, people lend hundreds of pounds to the people they love most on a nod, and hope it works out.”
Writing a loan down, he argued, does three things: it forces the conversation at the start, when everyone is on good terms; it puts both people in front of the same record; and it takes the lender out of the debt-collector role, because “the reminder comes from Pebblio, not from your sister.” Most importantly, it makes changing the plan normal. “‘Can I pay you late this month?' is the conversation that damages relationships. In Pebblio it's a request both sides see and agree to, and the repayment schedule updates automatically.” Every loan comes with a signed written agreement, but when people were asked what they wanted most, more than half chose a repayment schedule and automated reminders, and fewer than three in ten picked a legally binding contract.
Not a lender
The line between record-keeping and credit provision is one Postlethwaite draws firmly. “Pebblio never lends, never holds money and never collects on anyone's behalf. We're not a party to the loan and we provide no capital. We don't decide who can borrow or how much: no credit scoring, no affordability decisions, no marketplace matching strangers.” Money moves directly between the two people, by bank transfer or cash, and reminders follow the schedule both agreed. Before launch the company commissioned an independent regulatory assessment of the model against the FCA perimeter, specifically the rules on operating a lending platform. Keeping loans interest-free is part of the same principle: “If someone wants to make a profit from lending, Pebblio is the wrong product.”
What policymakers and lenders should take from it
His message to both is that informal lending is mainstream, not marginal: one in two adults, rising to nearly three in four among under-35s, and under-counted in official statistics because they count only borrowers and treat it as a financial product. For mainstream lenders, the lesson is that this is not a market they can serve. Half of people who lend or borrow moved under 250 pounds across the whole year, 58 per cent of lenders charge no interest, and only one in twenty would look to their own bank for a tool to manage these loans. “Lenders should recognise how much of their customers' finances runs through family and friends, not try to replace it.”
For policymakers, he said, the risk is not the lending but the lack of structure, and peer-to-peer rules written for platforms matching investors with strangers do not fit people lending to their own family. “So protect what works. Keep family lending outside consumer credit rules built for commercial lenders, and help people do it well instead: clear terms, a shared record and a route to free debt advice. When family can't help, the alternative is far worse. Fair4All estimates up to 1.9 million people used an illegal lender last year.”