
Mia Wealth's Sophia Jarvis on investing for children as a gift
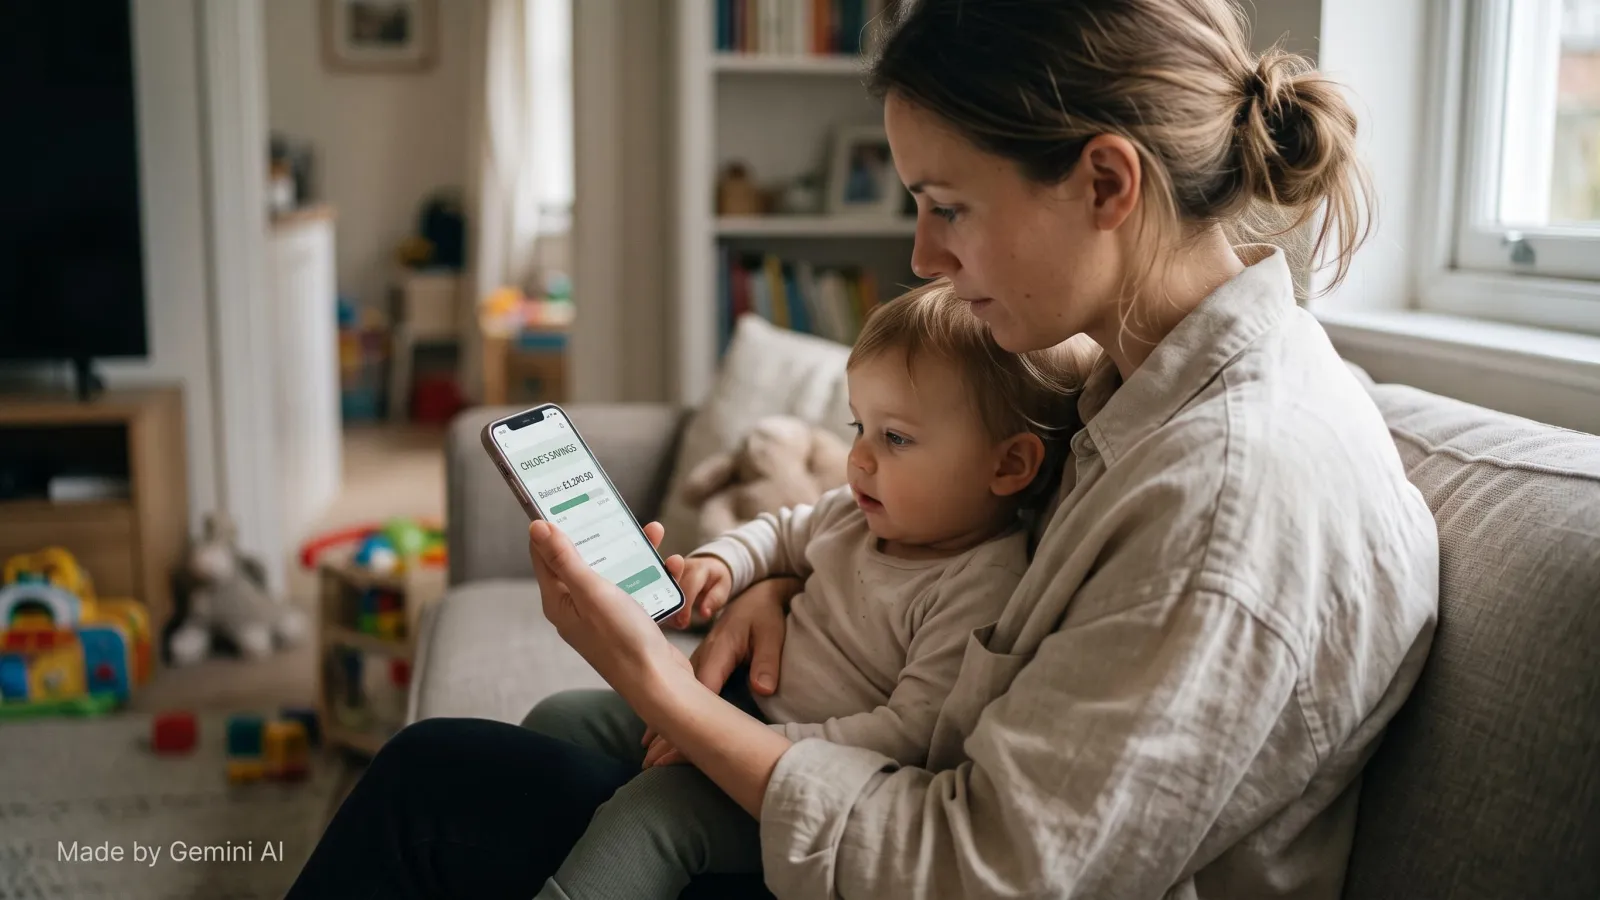
Mia Wealth is a new UK family investing and gifting app built to make investing for a child as easy as buying them a toy. Parents can open a Junior Stocks and Shares ISA from 20 pounds, family and friends can gift from 10 pounds through a personalised link, and a Junior Pension is due to launch in December. Custody sits with Seccl and the funds are managed by Fidelity and Aviva Investors.
Co-founder & CEO,
Mia Wealth
Its chief executive and co-founder, Sophia Jarvis, is a former wealth manager and a mother of twins. She told Disrupts why she framed the product around gifting rather than another investment account, what stops families using their Junior ISA allowance, and what a beta of 150 families taught the company.
A familiar reason to start
Jarvis saw the gap from both sides of the table. “As a wealth manager, I saw what starting early could do for a child. I also heard parents say they wished they'd started years ago. The intention was there, but children's investing often felt complicated, fragmented and easy to put off.” Having twins made it personal. “Loved ones wanted to give them something meaningful, but clothes were quickly outgrown and toys piled up. There wasn't an easy way to bring everyone together around their financial future.”
Gifting, she argued, solves the starting problem. “Gifting gives people a familiar reason to start: a birth, birthday or Christmas. It also means the responsibility doesn't sit entirely with the parents.” A gift can carry a voice, video or text message, so it keeps the story of who gave it and why. “That makes investing feel much more personal.”
Why the allowance goes unused
HMRC data suggests only a small fraction of the available Junior ISA allowance is used each year, and Jarvis is clear that affordability is the first reason. “Families are juggling childcare costs, housing and everyday bills. An unused allowance doesn't mean they have spare money to invest. It is important families focus on building up their own savings and pensions first.” Her answer is to redirect money that is already being spent: “We spend 3.9 billion pounds a year on toys for children. Redirecting even some of that spending into a child's investments could help build their future, without asking parents to find more money in the household budget.”
The second barrier is overwhelm. Parents who could start are “unsure which account to open or worried about getting it wrong. It becomes another job on an impossible to-do list.” Mia's response is a short onboarding and a default fund chosen by the child's age and the time until they turn 18. “Parents don't need to see the maximum allowance as a target. Smaller contributions and gifts from loved ones can help build a regular investing habit over time.”
How it works, for parents and for gifters
A parent or legal guardian downloads the app, completes account opening in a few minutes and opens a Junior Stocks and Shares ISA, a Junior Pension or both. They can start with 20 pounds, make one-off contributions or set a flexible monthly payment. They then share the child's personalised gifting link, and a grandparent, godparent or friend can give from 10 pounds without an account; afterwards gifters can download the app, see the children they gift to and contribute again whenever they choose.
Gifters can also leave a written, voice or video message for the child's Memory Box, unlocked at 18. “That's particularly meaningful to me,” Jarvis said. “The child can eventually discover the people and memories behind their gifts.”
Why not hold the assets
The company chose established infrastructure over building its own custody. “I spent years in wealth management, so I knew how important the infrastructure behind the app would be. Families deserve to understand who holds their child's money and who manages the investments.” Seccl provides custody, the funds are managed by Fidelity and Aviva Investors, and client money and investments are held separately from Mia's own business assets. “That separation matters when parents are entrusting us with money intended for their child's future.” It also keeps the team focused, she said, on the experience families need: “straightforward account opening, easy gifting, understandable information and responsive support.”
Designing for mothers
Jarvis describes mothers as an underserved investment customer, and serving them well “starts with taking their ambitions seriously. The mums we speak to care deeply about their children's futures. They often want to act but are juggling work, nursery, meals, appointments and a hundred other things.” The design questions follow from that reality: “Can they understand the product quickly? Complete the process between feeds or after bedtime? Find the fees and risks without hunting through pages of jargon? Get a helpful human response when they have a question?”
“As a mum to twins and a founder, I know how frustrating it is when something that should be straightforward becomes another project to manage. We want parents to leave Mia feeling informed and proud that they've started. We're building for every family, with mothers' needs deliberately included from the beginning.”
What the beta showed
The beta involved 150 families with around 290,000 pounds invested before public launch. Just over half set up monthly contributions, averaging 60 pounds a month. “The strongest lesson was how long some parents had been meaning to do this. We heard from people who'd had investing for their child on their list for years, then finally opened an account between feeds, dinner or bedtime. Making the process manageable helped turn intention into action.” The regular contribution matters most to her: “Opening an account is the beginning; building a sustainable habit is what we want to support.” The beta also showed the parent and gifting journeys needed clearer explanation, which the company has since reworked.
The Junior Pension, and what comes next
The Junior Pension, with Aviva Investors, is planned for December, in time for Christmas. “Parents will be able to build for two different stages of their child's life: a Junior Stocks and Shares ISA for adulthood and a Junior Pension for their much longer-term future.” Pensions are personal for Jarvis: “my dad started investing into one for me when I was young. Knowing that foundation was there changed how I thought about my future.” She wants more families to know that a child's pension is possible, and that contributions attract a 25 per cent bonus through basic-rate income tax relief.
Beyond that, the company is improving the gifting experience, developing financial education for children along the way and working towards an app experience for when they turn 18. “The ambition is to support the whole journey: family contributions today, growing understanding through childhood and confident ownership in adulthood.”
When you invest, your child's capital is at risk and its value can go down as well as up. Tax treatment depends on individual circumstances and may change. Money in a Junior Stocks and Shares ISA cannot be accessed until the child turns 18, and money in a Junior Pension cannot be accessed until the minimum retirement age, which may change.