
M-KOPA hits 10m customers and $600m revenue on Africa fintech surge
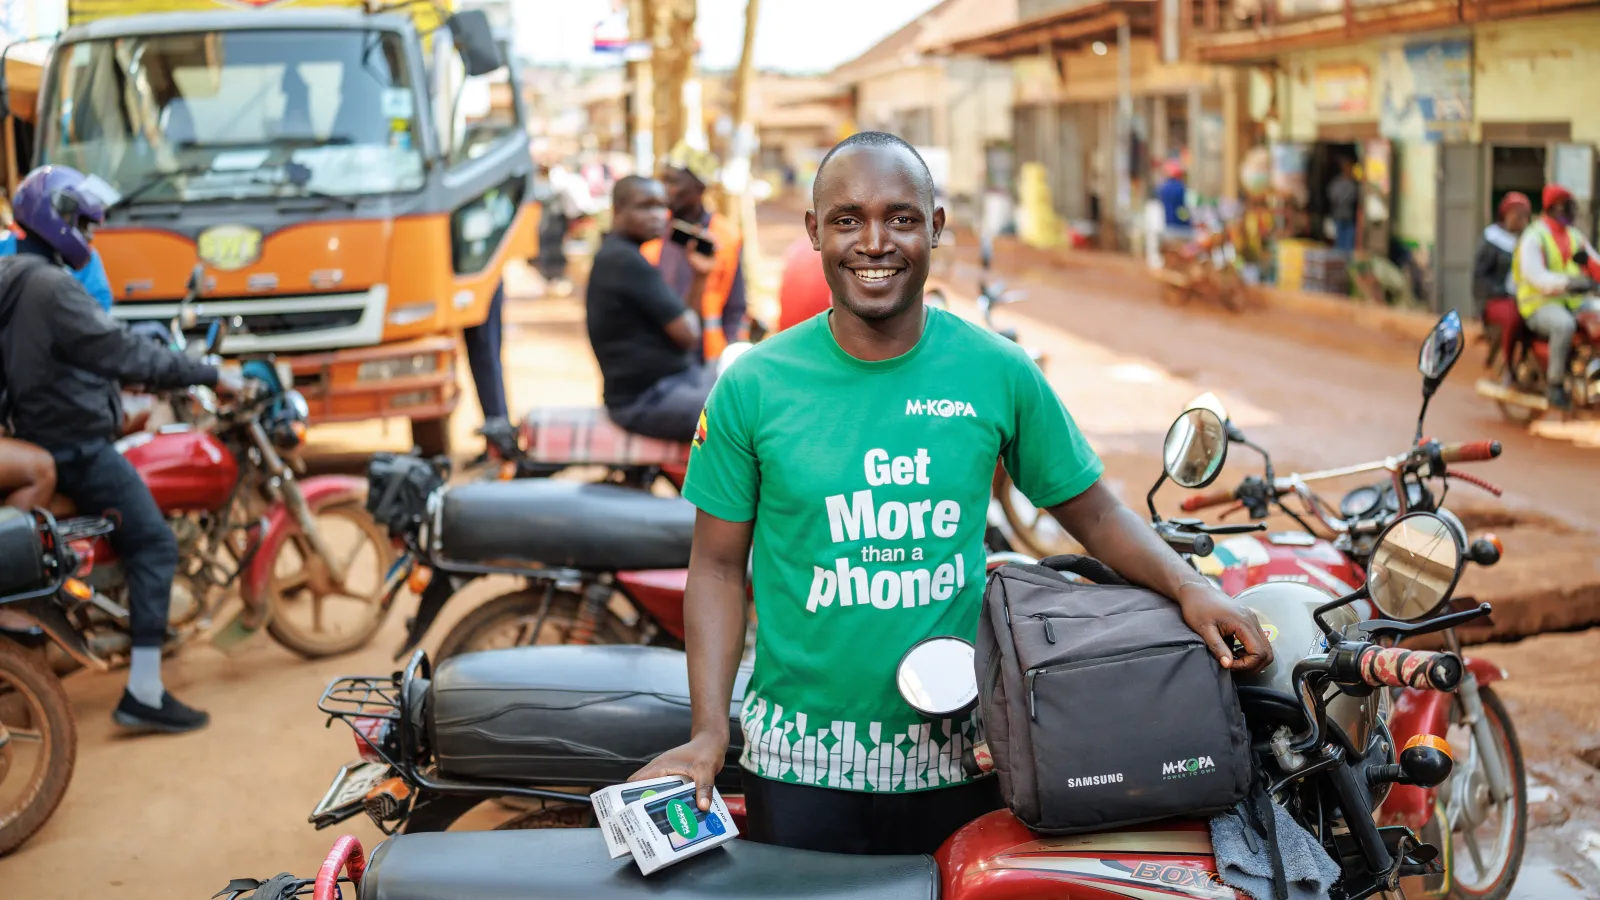
M-KOPA, the Africa-focused inclusive fintech founded in 2011, has reported record revenues of $600 million for its 2025 financial year, a 45% increase on the prior year, as it simultaneously crossed the 10 million customer mark. Three million of those customers joined in the past 12 months alone, with the company onboarding roughly 10,000 new users every day and processing micropayments at a rate of 23 times per second.
The numbers confirm M-KOPA as one of the most significant financial-inclusion stories on the continent, and arguably the clearest proof point that asset-backed micro-credit, rather than traditional bank lending, is the structural model for bringing Africa's informal economy into the digital financial system.
From solar panels to smartphones to electric mobility
M-KOPA's growth trajectory is itself a convergence story. It began as a provider of financed solar home systems, extending pay-as-you-go credit to households with no formal salary or credit history. In 2020 it pivoted into smartphone financing, and the compound annual growth rate over the five years since has been 50%. The smartphone is not merely a product: it is the onramp. Once a customer holds an M-KOPA handset, the device becomes the gateway to digital loans, savings, and now electric vehicle financing. The company says it has already financed more than 10,000 electric motorcycles and three-wheelers in Kenya, positioning itself as an early market leader in that segment.
That product arc, from energy access to connectivity to clean mobility, illustrates how a fintech platform can become a multi-sector infrastructure layer. Chief Financial Officer Faraimose Kutadzaushe put it directly: "We are still very early in our growth trajectory. We maintained profitability, while we focused on reinvesting as much as possible in our products, technology and distribution to continue to scale against a massive, underserved market of every day earners across Africa."
The manufacturing move and its macro implications
Perhaps the most strategically significant disclosure in this announcement is not the revenue figure but the manufacturing decision. M-KOPA has opened what it describes as Africa's largest smartphone assembly factory in Kenya, supported by technology acquisitions and its own X4-series handset line. For a fintech to move upstream into hardware manufacturing is unusual; it signals that M-KOPA views affordable device supply as a structural constraint on its own addressable market, one it has decided to control rather than outsource.
This move sits within a broader trend that cross-sector investors should note. Several African markets are actively building domestic manufacturing capability in electronics and clean-energy hardware, partly driven by global supply-chain fragmentation and partly by industrial-policy incentives. Kenya's Special Economic Zones and the broader African Continental Free Trade Area framework are creating new cost structures for assembly operations. M-KOPA's factory is therefore both a competitive moat and a signal about where production geography is shifting in the mid-cap consumer electronics space.
The electric mobility angle compounds the convergence logic. M-KOPA is not competing with traditional insurers or banks for its customers; it is competing with informal moneylenders and, increasingly, with the absence of any financial product at all. Its distribution network of nearly 50,000 sales agents, spread across Kenya, Uganda, Ghana, Nigeria and South Africa, functions as a last-mile financial infrastructure that no incumbent bank has replicated at comparable scale or cost. With $2 billion in cumulative credit unlocked and more than 2 million payments processed daily, the platform is beginning to generate the data density that underpins sophisticated credit scoring, a capability with significant implications for insurance, supply-chain finance, and sovereign digital-ID programmes across the five markets it operates in.
For macro investors watching Africa's digital economy, M-KOPA's trajectory points to a model in which the device, the credit facility, and the clean-energy asset are bundled into a single relationship with an everyday earner. That bundling, replicated at scale across a continent of 1.4 billion people, represents a capital-allocation thesis that remains underweighted in most institutional emerging-market portfolios.